海外旅行保険は、加入の有無だけでなく「何が、いくら、どんな条件で補償されるか」が重要です。クレジットカードを持っているだけでは適用されない利用付帯や、家族が対象外の契約もあります。
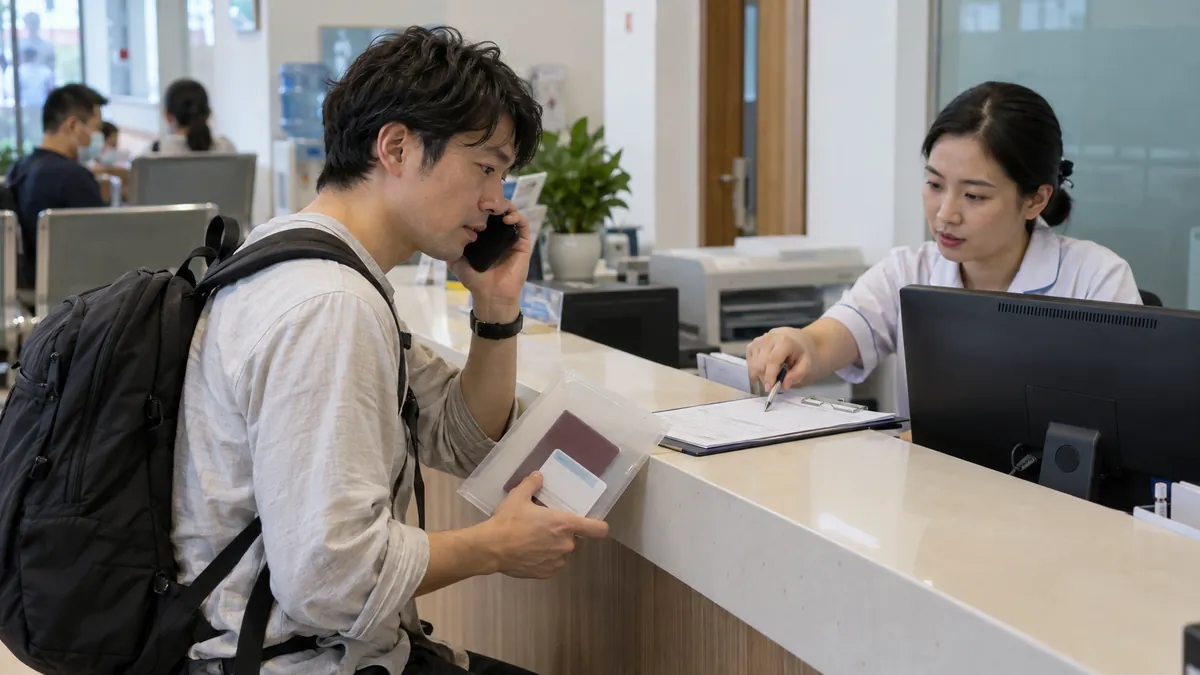
選ぶときは、治療・救援費用、キャッシュレス診療、既往症、携行品、航空機遅延を契約書で確認します。この記事の金額は一般論にせず、カード会社・保険会社の約款とサポート窓口を最終判断にしてください。
先に確認する5項目
- 自動付帯か利用付帯か、利用付帯なら何の決済が条件か
- 本人だけでなく同行する家族も対象か
- 治療・救援費用の上限と免責金額
- 滞在都市にキャッシュレス診療の提携先があるか
- 既往症、妊娠、歯科、置き忘れなど対象外条件は何か
Why overseas travel insurance is necessary
- Treatment costs tend to be high—private hospitals for foreigners are expensive, and when hospitalization and transport pile up it becomes a large expense
- You can use cashless treatment——事前承認や契約条件を満たせば、保険会社の直接精算で立替を減らせる場合がある
- Personal belongings and liability are covered too—a broken or stolen smartphone, and liability toward third parties, may also be covered
The difference between credit-card-attached and optional coverage
The insurance attached to a card may cover things, but coverage amounts and conditions differ. The realistic approach is to understand the difference between the two and supplement the shortfalls with optional insurance.
| Credit-card-attached | Easy and no extra cost. However, the treatment-cost limit is on the low side, and it may be usage-linked (with conditions such as paying travel costs by card) |
|---|---|
| Optional insurance | You can beef up treatment and rescue costs and choose the coverage. You can enroll online or at the airport before departure |
| Combination | Using card-attached coverage as the base and topping up shortfalls in treatment and rescue costs with optional insurance gives peace of mind |
Points for choosing
- Prioritize treatment and rescue costs—check whether the amount limit is sufficient and whether it covers local transport and hospitalization
- Partner hospitals for cashless treatment—check whether there's a partner hospital in the city you're staying in
- Belongings, liability, flight delays—whether trouble with your smartphone, camera, or checked baggage is covered
- Conditions of card-attached coverage—always check whether it's automatically attached or usage-linked, and the coverage period (often 90 days from departure, etc.)
Main coverage items
| Treatment and rescue costs | Treatment costs for injury/illness, hospitalization, family rushing over, and transport. The item to prioritize most |
|---|---|
| Belongings damage | Damage or theft of a smartphone, camera, or luggage (with a deductible and limit) |
| Liability | Compensation when you injure someone or break something |
| Flight delay/cancellation | Coverage for lodging and meal costs incurred by a delay or cancellation |
| Emergency assistance | 24-hour Japanese-language support and arranging partner hospitals |
The flow of cashless treatment
"Cashless treatment" at a partner hospital is a system that lets you be seen without fronting a large sum on the ground. If you fall ill, the basic flow is to first call the insurer's 24-hour assistance and have them direct you to a partner hospital.
- Cashless——事前に保険会社へ連絡し、承認された提携病院を受診します。契約範囲外の費用や保証確認前は立替が必要になる場合があります
- Pay upfront—at a non-partner hospital, you pay once yourself and claim after returning home by submitting the statement and diagnosis certificate
- What to prepare—keep your policy number and emergency contacts on both your smartphone and paper
The pitfalls of card-attached coverage
- Usage-linked conditions—the insurance may not be valid unless you pay travel or transport costs with that card
- Coverage period—the period is set, such as up to 90 days from departure, and it can lapse on a long stay
- Treatment-cost limit—attached insurance often has a low limit, easily falling short when hospitalization and transport pile up
- Family / companions—only the primary member is covered, and family may need separate coverage
- 複数契約の扱い——治療費用や携行品などは、実際の損害額を超えて二重に受け取れるわけではありません。死亡・後遺障害を含む支払方法は契約の組み合わせで異なるため、自己判断で単純合算せずカード会社・保険会社へ確認します
How to use insurance by type of trouble
Knowing in what situations insurance actually helps lets you act calmly when the time comes. Using trouble common on Vietnam trips as examples, we organize the flow of response.
| Food poisoning / sudden fever | First call the insurer's 24-hour assistance and have them direct you to a partner hospital. Covered by treatment and rescue costs. After being seen, be sure to get a diagnosis certificate and receipt |
|---|---|
| Injury from a motorbike or traffic accident | Covered by treatment and rescue costs. If hospitalization or transport to Japan becomes necessary, costs balloon, so whether the limit is sufficient matters. If you can obtain an accident report, keep it on hand |
| Theft or pickpocketing of a smartphone or camera | Handled by belongings damage. A claim requires proof of a theft report issued by the police (a police report). When you notice the loss, have the local police issue one |
| Flight delay or cancellation | If it's a product with flight-delay coverage, you can cover lodging and meal costs unavoidably incurred. Keep the airline's delay certificate and receipts |
Documents needed for an insurance claim
To make your claim after returning home smooth, gathering evidence on the ground is above all important. Many documents can't be obtained later, so make it a habit to get them or photograph them on the spot.
- When you receive treatment—a doctor's diagnosis certificate (one showing the injury/illness name) and the treatment-cost receipt and statement
- When there's theft or damage—proof of a theft report from the police (a police report), and the purchase receipt or a photo identifying the product
- When there's a delay or cancellation—the airline's delay/cancellation certificate, and receipts for the additional lodging and meals paid
- Common—your policy number, a copy of your passport, and something showing your boarding pass or itinerary
How to think about coverage-amount guidelines
Which items you prepare heavily for changes both the premium and your peace of mind. Choosing with priorities lets you secure the coverage you need without waste.
- Beef up treatment and rescue costs as the top priority—overseas hospitalization and medical transport to Japan tend to be costly, so make this the most robust
- Cover belongings on an actual-expense basis—if you bring expensive devices like a smartphone or camera, check the deductible and the per-item limit
- Cash and expensive valuables tend to be excluded—belongings coverage often excludes or heavily limits cash, jewelry, and precious metals. To guard against theft, carry them dispersed and don't bring too many valuables
- Liability and delay coverage give peace of mind if attached—liability toward others and flight delay make reassuring support if attached
Timing of enrollment
The basic approach for optional insurance is to enroll online before departure. Even if you forget to apply, you may be able to enroll at an airport counter or online on the day of departure. However, many products can't be enrolled in after you've left the country, so completing the procedure at the latest before departure gives peace of mind.
Frequently asked questions
- Is overseas travel insurance necessary for a Vietnam trip?
-
必須ではありませんが、外国人向け病院の治療費は高額になりやすく、加入をおすすめします。キャッシュレス診療が使える契約でも事前連絡や承認が必要なことがあり、契約外費用は自己負担です。
- Is a credit card's attached insurance enough on its own?
-
Card-attached coverage is easy, but the treatment-cost limit may be on the low side, or paying travel costs by card may be a condition (usage-linked). Supplementing shortfalls in treatment and rescue costs with optional insurance gives peace of mind.
- When should I enroll in insurance?
-
The basic approach is online enrollment before departure. Some products can be enrolled in at the airport on the day, but since many can't be enrolled in after you've left the country, complete the procedure at the latest before departure.
- What do I need for an insurance claim if I'm robbed?
-
A claim for belongings damage generally requires proof of a theft report issued by the police (a police report). When you notice the loss, have the local police issue one. Note that cash and expensive valuables tend to be excluded from belongings coverage, so checking the policy terms gives peace of mind.
- Can the treatment costs of multiple credit cards be combined?
-
Actual-expense coverage such as treatment costs and belongings damage can sometimes be combined across multiple cards that meet the conditions. On the other hand, death and residual disability are generally based on the highest amount. It's a good idea to check the coverage amounts of the cards you hold once.
Also check the notes on local safety and water together.
まとめ:カードの有無ではなく、補償の発動条件を見る
カード付帯で足りるかは、利用条件、期間、治療・救援費用、家族の対象範囲で決まります。保険証券番号、緊急連絡先、契約内容をオフライン保存し、受診前に連絡できる状態を作ってください。補償の可否は診断名や事故状況でも変わるため、記事ではなく約款と保険会社の回答を優先します。